


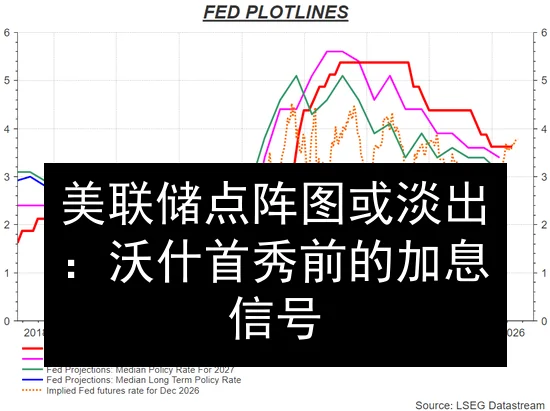
Fed Dot Plot May Fade: Hawkish Signals Ahead of Warsh's Debut
The Federal Reserve's quarterly “dot plot” interest rate projections may soon lose their last rate-cut signal, or even be eliminated entirely. Then markets will have to judge whether Fed Chairman Kevin Warsh is truly the inflation hawk he has claimed to be. If so, it may catch some investors off guard.
The new Fed chairman is busy establishing his position and consulting staff ahead of his first policy meeting later this month. Any guidance he derives from the policy trajectory will hardly yield a simple answer.
The astonishing growth in artificial intelligence investment and the energy price surge from the three-month-old Iran war have pushed inflation well above target. Combined with internal uncertainties at the Federal Open Market Committee, futures markets are nervous, expecting the next rate hike before year-end.
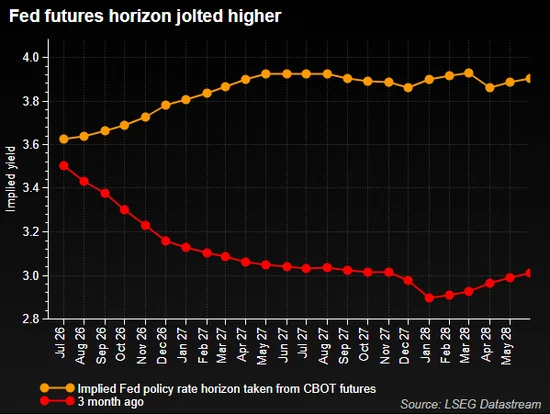
In recent months, one of the few remaining arguments for doves was that the labor market (the other side of the Fed's dual mandate) could show cracks, possibly exacerbated by AI-related layoffs or energy-related business shutdowns. But there is almost no sign of that yet.
Instead, there are indications the job market appears strong, possibly even improving. A sharp rise in job openings in April and a better-than-expected gain of 122,000 private-sector jobs in May point to that. The national nonfarm payrolls report for May will test this trend when released Friday.
The Fed will not hike rates this month, but could plant seeds for a hike.
Beyond any signals from Warsh at the press conference, markets will closely watch whether the Fed's previous statement's hint of another rate-cut bias is removed. Three board members already voted to remove that language at the last meeting, and at least one previously dovish Fed governor (Waller) has joined them since then.
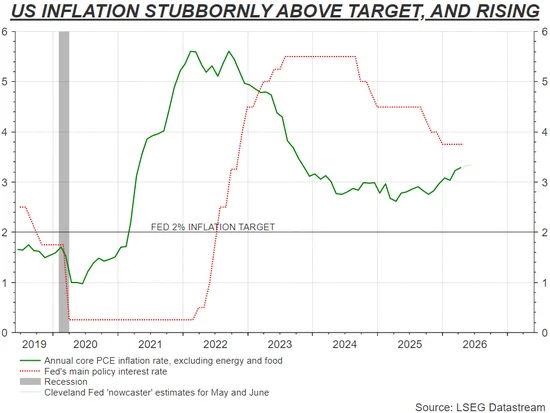
But the quarterly economic projections from Fed policymakers, including the “dot plot” forecasting interest rates over the next few years, may become the focus.
The current median projection includes one more rate cut this year and another in 2027.
Since March, various comments from Fed officials suggest the rate-cut expectation for this year is likely to vanish from the dot plot. Whether there will be a rate cut in 2027, or even a rate hike as markets expect, may have the greatest shock on markets.
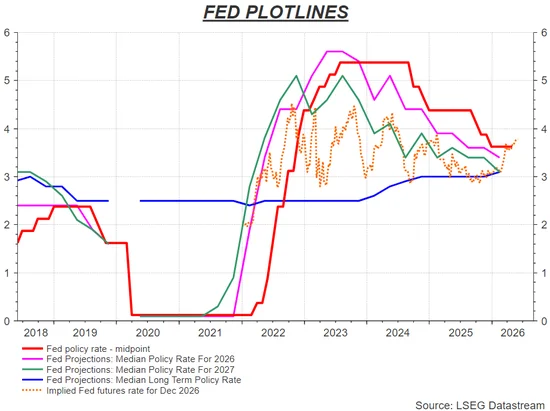
Of course, the irony is that Warsh's aversion to so-called forward guidance may push him to abolish the “dot plot” altogether. He would have many supporters—including his predecessor Jerome Powell, who remains a Fed governor.
If further easing prospects are removed and guidance is stopped, leaving markets to judge based on new data on their own, the rate market could become more tense and volatile in the second half of the year.
Of course, some investors still hope that an eventual end to the Iran war will put easing back on the table, or that the impact of energy austerity on real income will be enough to curb household demand and thus control other prices.
But many believe the tide has already turned.
Rate Cut Plans Halted Abruptly
Tim Duy, an economist at SGH Macro, believes the inflationary consequences of higher energy prices now dominate the impact on economic growth, and as the Fed begins to realize that the last rate cut in December was a mistake, the stance within the FOMC is shifting rapidly.
“Fed officials are increasingly aware of the risk of inappropriate monetary policy and are quickly pivoting hawkish to pave the way for rate hikes,” he said.
“The old Warsh would raise rates early,” he added, referring to Warsh's long-standing reputation as a monetary hawk. “No one knows which version of Warsh will show up.”
Despite headwinds from energy, geopolitics and tariffs, the economy and stock market continue to heat up thanks to the AI investment boom, leading many to question why the Fed would consider easing again.
Warsh's rethinking and adjustment may deviate from many expectations.




