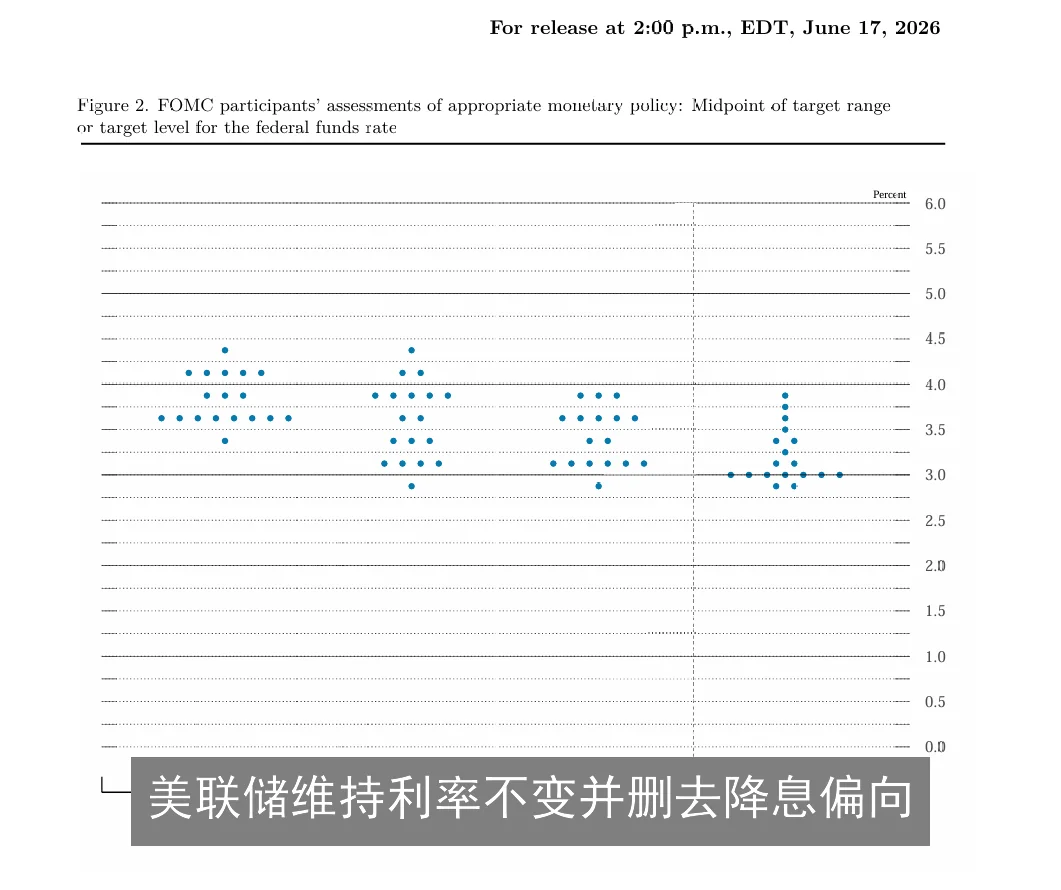
Fed Holds Rates Steady, Removes Easing Bias
The first meeting chaired by Fed Chairman Kevin Warsh concluded Wednesday, with the Federal Open Market Committee (FOMC) voting to hold rates steady and removing key language suggesting a future bias toward easing, while significantly shortening the policy statement.
The FOMC voted unanimously to keep the benchmark overnight lending rate in the range of 3.5% to 3.75%. The rate has been at this level since the central bank cut rates by 0.75 percentage points in the second half of 2025.
Despite market focus on Warsh's leadership, the meeting continued the established pattern on the rate decision, but policy language clearly turned more cautious.
The Fed withdrew expectations for rate cuts this year via the closely watched “dot plot,” and hinted that rate hikes are possible but not certain. However, the dot plot was missing one member's forecast, leading market observers to suspect Warsh did not submit his projections.
A note attached to the projections showed that 18 of the 19 participants submitted interest rate and economic forecasts. Since the dot plot is anonymous, it is impossible to confirm whether the missing submission was indeed Warsh. But before the meeting, the market widely expected Warsh would not participate in the Summary of Economic Projections (SEP). Some also speculated he might try to eliminate the mechanism. Additionally, a dot was missing from the 2028 projections.
Warsh has long criticized the dot plot forecasting tool and other forward guidance from the committee, including GDP, unemployment and inflation forecasts in the SEP.
Beyond the widely expected rate decision, the post-meeting statement not only removed language suggesting a future bias toward easing but also significantly cut the rest of the content. This week's statement was only 130 words, compared to 341 words after the previous meeting on April 29.
The statement briefly summarized economic conditions, then pledged to control inflation. The statement said: “Despite some degree of uncertainty, partly due to the Middle East conflict, economic activity has been expanding at a solid pace. Productivity growth and capital investment have been strong. Job growth has kept pace with the labor force, and the unemployment rate has moved little.”
The committee added: “Inflation remains above the Committee's 2% objective, partly due to supply shocks pushing up prices in some areas including energy. The Committee is committed to achieving price stability.”
The statement also noted the Fed would maintain its policy of keeping “ample reserves” in the banking system, indicating no immediate plan to shrink the central bank's $6.7 trillion balance sheet of bond holdings, despite Warsh's advocacy for such action.
At the previous April meeting, there were three dissenting votes as regional bank presidents wanted to keep the option of future rate increases or decreases, opposing the so-called “forward guidance” language. This statement passed unanimously.
With interest rate outlook highly uncertain, officials also adjusted their guidance on future policy direction. The dot plot, which anonymously shows participants' rate expectations, erased the previous expectation of one rate cut this year and pushed any possible cuts to 2027 and 2028, as policymakers assess the persistence of inflation spurred by the Iran war.
The median end-year federal funds rate projection was 3.8%, about 0.16 percentage points above the current level, indicating rate hikes are being considered. Officials continue to project the long-run federal funds rate at 3.1%.
Officials also raised their inflation judgment for the economy, revising the 2026 headline inflation forecast to 3.6% and core inflation (excluding food and energy) to 3.3%. In the previous update in March, both were 2.7%. They also slightly lowered GDP growth expectations to 2.2%, down 0.2 percentage point from March; unemployment expectations were lowered to 4.3%, down 0.1 percentage point.
The inflation surge puts policymakers in a dilemma, as traditional policy training calls for looking through short-term supply shocks, such as war-related energy price increases. Recent inflation readings hit multi-year highs, with the May Consumer Price Index showing an annualized rate of 4.2%, although the core measure excluding food and energy was lower at 2.9%. Inflation has been above the Fed's 2% target for the past five years.
Although Warsh has made few public comments before being sworn in as chairman on May 22, he has long argued that policy should generally look through supply-shock inflation. He also believes that artificial intelligence will ultimately have a disinflationary effect on the economy, as productivity gains will help lower goods and services costs.
However, the unexpectedly strong labor market complicates the case for rate cuts. May nonfarm payrolls again exceeded expectations, adding 172,000 jobs, while the unemployment rate, which the Fed watches most closely, has remained at 4.3% for the past year.
Market pricing aligns with the FOMC projection. According to the CME FedWatch tool, markets expect no rate cuts in 2026 and anticipate a 25-basis-point rate hike by year-end.