2026 MWC Shanghai observations: 6G shifts from “what to do” to “how to do it,” while satellites enter a scale-up cost-down phase
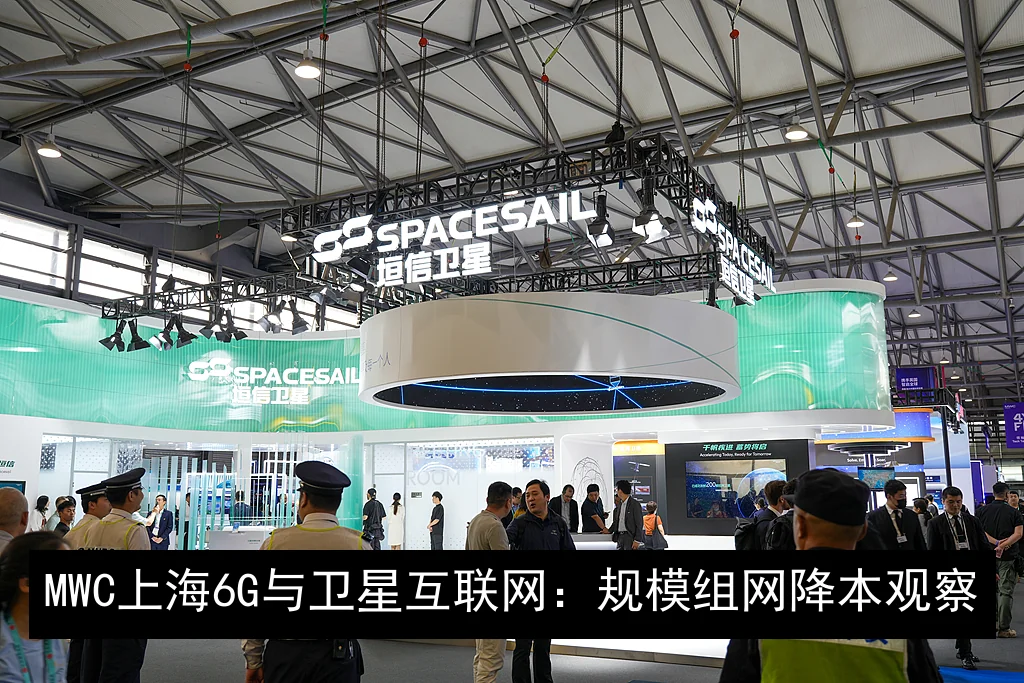
2026 MWC Shanghai opened as scheduled. Unlike last year’s upbeat atmosphere of dense 5G-A commercial orders, this year’s exhibition hall feels more cautious and pragmatic. The newly independent “6G Industry Ecosystem Zone” and the “Future Constellation” satellite zone are both popular, but the industry is more interested in turning technology into cash flow.
Blue Whale Tech reporters found that in the 6G space, the three major paths — integrated sensing and communication, AI-native, and space-air-ground integration — are no longer controversial, and chipmakers have even started pre-research inventory. In satellite internet, the battle over orbital and frequency territory is basically over, and scale deployment plus cost reduction are now the new theme. Yet consensus stops at the technical layer. Terminal makers and investors are still waiting: the former for killer apps, the latter for a clear payback cycle. Even profitable international satellite players are struggling in the early stage of consumer market cultivation.
As the financial bill for 5G investment is not yet fully settled, 6G and satellite internet are jointly entering a transition phase of “clear vision, hard monetization.” The technology routes are getting narrower, but the commercial path looks wider. Under real-world ROI constraints, the industry needs a more practical answer than a grand narrative.
6G technology paths are converging, but the commercial loop is still being explored
Walking into the 6G ecosystem area in Hall N3, five sections — Beijing 6G Lab, communication enhancement, integrated sensing and communication, integrated communication-computing-intelligence, and space-ground integration — make the core vision of 6G easy to grasp. Staff said this is the first time MWC Shanghai has given 6G its own hall, sending a very clear signal: 6G has moved from concept discussion into a key phase of system validation.
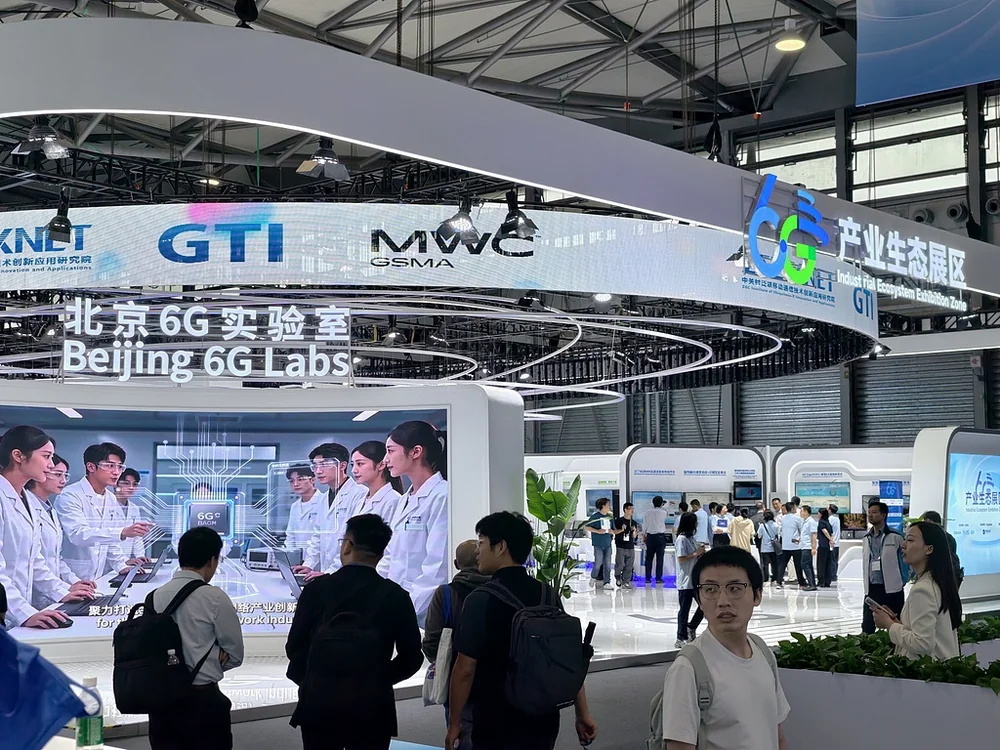
“If people were still arguing last year about what 6G should do, this year the debate is about how to do it — and what tradeoffs to make,” a technical staff member in the Beijing 6G Lab told reporters. At present, the three enhancement paths — integrated sensing and communication, AI-native, and space-air-ground integration — have largely formed an industry consensus. Key technologies such as terahertz communication and intelligent metasurfaces are now entering prototype validation.
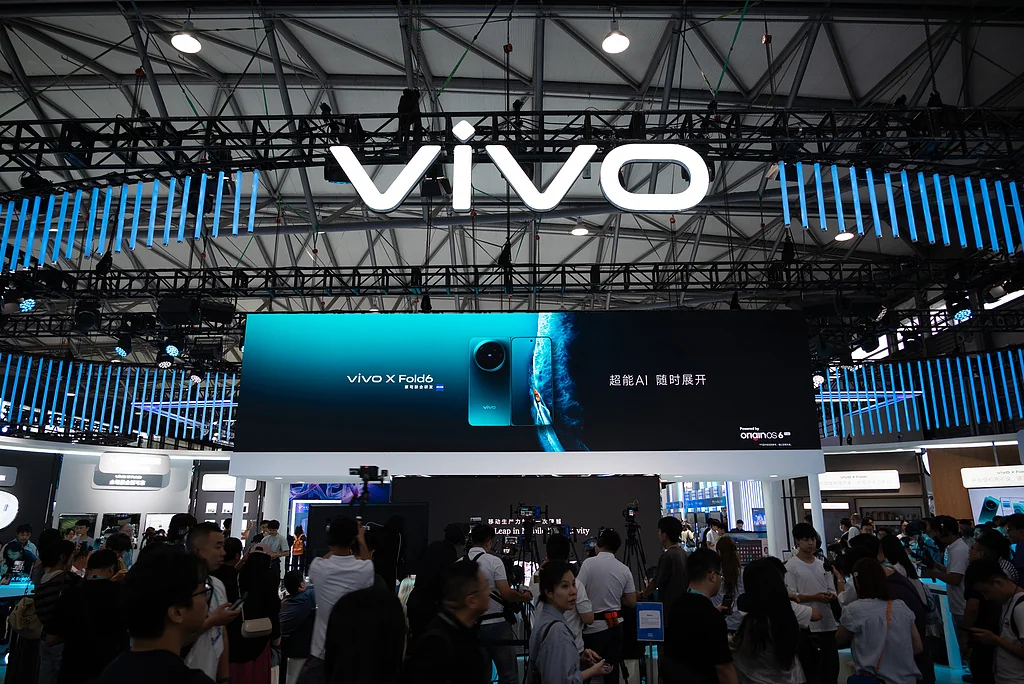
Upstream supply-chain planning is clearly accelerating. At this exhibition, Qualcomm showed an end-to-end 6G prototype system. GalaxySpace publicly displayed its self-developed second-generation direct-to-phone phased-array antenna for the first time in the 6G zone. vivo also presented its 6G pre-research prototype and roadmap. Compared with Xiaomi’s focus on transport algorithms and OPPO’s focus on communication paradigm innovation, vivo’s demo is more end-to-end and application-oriented. Its full 6G test system covers the entire chain, including MR terminals, 6G UE prototypes, 6G base stations (RAN), and the core network.
A domestic chipmaker’s on-site executive told reporters that the company’s 6G pre-research team is now twice as large as last year’s. The logic is simple: “If you wait until the standard is frozen, you’re already late. You have to build the technical reserve ahead of time.”
But compared with the upstream enthusiasm, terminal makers are much more cautious. When Blue Whale Tech asked several phone brands about their 6G terminal roadmap, most replies were essentially “we’re watching closely,” and there were few consumer demos for 6G on the show floor. One 6G R&D head from a top-five global phone maker said in informal conversation that it’s still hard to produce a clear 6G smartphone commercialization roadmap. The issue is not lack of technical capability; rather, the path from terminal capabilities to user demand and application scenarios is still being assessed. In his view, the 5G experience dividend has not yet been fully absorbed, and 6G concepts like immersive holography and multi-sensory interaction are still far from mass-market adoption.
The investment community is equally cautious. At the exhibition, a TMT-focused early-stage investor who had watched several demos said the technical direction is impressive, but from an investment perspective, the capital return from 5G is still being digested, and the R&D and network-deployment spending required for 6G is enormous. Exit cycles and return expectations still lack enough data support. He admitted that, for now, he’s more in observe-and-track mode, waiting for clearer commercial signals before committing capital.
“Future Constellation”: the layout is set, but profitability still needs proof
Compared with the technical-validation atmosphere in the 6G area, the newly created “Future Constellation” satellite zone presents a different industry rhythm. The orbital layout is beginning to take shape, and participants are now moving into a phase of careful scale and cost optimization.
Companies including China Spacesat, Guodian Gaoke, and Yunsheng Satellite, along with international player Iridium, all set up sizable booths. China Spacesat showcased real low-Earth-orbit terminal devices for ocean shipping and desert mining scenarios. Guodian Gaoke focused on the Tianqi constellation’s IoT use cases. Yunsheng engineers even did a live link and played a video-call test based on the “Qianfan constellation.”
“The orbital and frequency resource battle in satellite internet is basically over. The key now is scale deployment and cost control,” a Guodian Gaoke representative told Blue Whale Tech. He said the mass-production cost of the company’s narrowband payloads is falling steadily, but also noted that user scale is still below breakeven, so government and industry orders remain the basic revenue anchor for the next few years.
Terminal cost is another important piece in the monetization path. Reporters asked antenna and module vendors about the bill-of-materials cost of satellite communication terminals, and most said costs are dropping quickly and can now be integrated into mainstream device designs, but they wouldn’t share exact numbers.
An Iridium business manager said the company has already achieved positive cash flow through narrowband voice and low-speed data services, but its traditional market is nearing saturation, so future growth must come from IoT and emergency communications. Domestic LEO broadband constellations are still in a catch-up phase focused on scale, and breakeven will require time and user accumulation.